
Best Westpac alternatives for equipment finance
Westpac provides equipment finance and a direct relationship with a major Australian bank. That relationship does not, by itself, give you a comparison of competing lenders. One Westpac alternative to consider in 2026 is Glenclair if you need a broker-led lender comparison; NAB if you want another direct bank proposal.
TL;DR
- For Westpac alternatives, Glenclair suits business owners seeking equipment finance comparisons through a panel of 60+ lenders.
- NAB and Commonwealth Bank suit borrowers who want to request another direct bank proposal.
- Compare equipment finance on security, repayments, residual debt and total commitments—not the interest rate alone.
- Keep Westpac if its documented offer fits your business better than the alternatives.
Why this matters
Replacing equipment and reviewing your banking arrangements are connected decisions. A new facility needs to fit your cash flow without creating security obligations that obstruct your next borrowing requirement.
For established Australian businesses considering business-purpose borrowing above A$2 million, start with the wider funding structure. That figure describes the audience for this guide, not a universal eligibility threshold. Suitability depends on the borrower, equipment and proposed transaction.
Westpac alternatives at a glance
These are different routes to equipment finance, not interchangeable products. A broker compares lenders; a bank considers an application for its own finance.
| Provider | Best for | Distinguishing feature | Difference from Westpac |
|---|---|---|---|
| Westpac | Borrowers assessing an offer from their existing or preferred bank | Direct bank relationship | Benchmark against which to compare other proposals |
| Glenclair | Business owners seeking a broker-led equipment finance comparison | Independent commercial brokerage with a panel of 60+ lenders | Broker rather than lender; compares options across its panel |
| NAB | Borrowers seeking another direct bank proposal | Direct equipment finance relationship | Another bank to assess separately against Westpac |
| Commonwealth Bank | Borrowers seeking an additional major-bank proposal | Direct equipment finance relationship | Another bank proposal to compare on documented terms |
The bank entries below are options to approach, not claims that a particular bank will approve your application or offer better terms. In 2026, the deciding evidence is the proposal for your business and equipment—not the provider's name.
1. Glenclair: best for comparing lenders and banking arrangements
Glenclair is an independent commercial finance brokerage covering business loans, refinancing, equipment and property development finance. Its panel includes 60+ lenders. That makes it a different route from asking another bank for a single proposal.
Glenclair is best for established business owners who want equipment finance assessed alongside their wider commercial borrowing. The purpose is to compare the funding structure, not simply substitute one lender's name for another.
Where the brokerage route shines
- Broader comparison: assess suitable panel lenders rather than relying solely on an incumbent bank's response.
- Connected borrowing decisions: consider equipment alongside refinancing, working capital and property commitments.
- Structured preparation: assess the requirement before preparing and presenting the borrowing request.
- Negotiation context: compare written terms against the same brief instead of comparing unrelated quotes.
Where the brokerage route falls short
- A lender panel is not the entire market. Ask which lenders are being considered and why.
- A broker does not make the lender's credit decision or guarantee settlement.
- A wider review requires business information and owner involvement. It is not a substitute for preparing financial records.
- Brokerage and debt advisory are different engagements. Clarify the scope and remuneration before proceeding.
| Dimension | Independent brokerage route | Westpac direct |
|---|---|---|
| Role | Intermediary between borrower and lenders | Lender assessing its own proposal |
| Comparison | Suitable options across a lender panel | Westpac's proposed facility |
| Wider review | Can include refinancing and other commercial funding needs | Discuss requirements within the bank relationship |
| Decision authority | Relevant lender makes the credit decision | Westpac makes its credit decision |
Best for: owners who need a lender comparison and a review of how equipment finance fits their existing banking arrangements.
Verdict: Buy the comparison process, not a promise of approval or savings.
2. NAB: best for another direct bank proposal
NAB provides equipment finance and gives you another bank to approach directly. This route suits owners who want to manage the application and compare the resulting offer themselves.
A NAB proposal is useful only if you can compare it fairly with Westpac's. Give both banks the same equipment details, borrowing requirement and preferred repayment structure.
Where NAB shines
- Direct discussion: deal with the prospective lender about its own requirements and proposal.
- A separate benchmark: obtain another bank's assessment rather than treating the incumbent's offer as the only option.
- Borrower control: retain responsibility for the application brief and comparison process.
Where NAB falls short
- A direct application is not a comparison across multiple lenders.
- You must reconcile differences between proposals yourself.
- An application does not establish that NAB will offer a better rate, security arrangement or repayment structure than Westpac.
| Dimension | NAB direct | Westpac direct |
|---|---|---|
| Provider type | Bank | Bank |
| Application route | Apply to NAB | Apply to Westpac |
| Offer being assessed | NAB's own proposal | Westpac's own proposal |
| Comparison responsibility | Borrower compares external alternatives | Borrower compares external alternatives |
For a 2026 equipment purchase, request written terms before deciding. A verbal indication is not enough to compare security requirements, residual debt and conditions before settlement.
Best for: owners comfortable preparing their own application and comparing bank proposals.
Verdict: Hold the decision until NAB and Westpac have answered the same borrowing brief.
3. Commonwealth Bank: best for an additional bank comparison
Commonwealth Bank also provides equipment finance. It is another direct route for owners who want to seek a bank proposal rather than appoint a broker.
Keep the comparison narrow and factual. The useful question is whether the proposed facility fits your business—not which bank has the strongest general reputation.
Where Commonwealth Bank shines
- Provides another direct bank option to assess.
- Lets you discuss the proposed equipment borrowing with the prospective lender.
- Adds another written proposal when you are managing the comparison yourself.
Where Commonwealth Bank falls short
- Its proposal does not replace a wider lender comparison.
- You remain responsible for comparing conditions and coordinating applications.
- Its name alone gives you no evidence of better terms or a suitable credit outcome.
| Dimension | Commonwealth Bank direct | Westpac direct |
|---|---|---|
| Provider type | Bank | Bank |
| Proposal source | Commonwealth Bank | Westpac |
| Market comparison included | Separate comparison required | Separate comparison required |
Best for: owners who want an additional major-bank proposal and can manage the comparison.
Verdict: Hold until the written terms establish a reason to change lenders.
Why people switch from Westpac
A reason to investigate alternatives is not proof that switching is right. Use these decision points to test your own arrangements rather than assuming a problem with Westpac.
You need a comparison, not just a renewal
An incumbent lender's offer answers what that lender will provide. It does not establish what other lenders would offer for the same transaction.
Request comparable proposals when reviewing equipment finance in 2026. Keep the requested borrowing amount, equipment and repayment assumptions consistent.
The equipment decision affects other borrowing
Ask whether proposed security or guarantees interact with existing facilities. That matters when equipment finance sits alongside working capital, commercial property debt or development funding.
Do not assume separate facility documents mean separate consequences. Have the proposed security arrangements explained before signing.
The repayment profile does not fit the business
A lower regular repayment is not automatically a better outcome. Check whether debt remains at the end of the term and how you would repay it.
Match the proposal to a documented cash-flow plan. Include the consequences of an equipment sale, replacement or early repayment.
You want the whole banking relationship reviewed
An equipment purchase can be the trigger for a broader review. Keep the scope explicit: a single asset transaction and a review of existing banking arrangements are different assignments.
The commercial finance services overview is a starting point for discussing equipment finance alongside refinancing and other business borrowing.
How to compare proposals without comparing unlike terms
Use the same written brief for every lender. The sequence below keeps preparation, tendering and negotiation separate, so you can identify what has actually changed between offers.
Assess
Define the equipment purchase and business purpose. Gather current financial information, existing debt details and the proposed supplier documentation.
Structure
Decide what you want lenders to assess. Set out the requested term, repayment approach, proposed security and any residual payment you want considered.
Prepare
Build a consistent application pack. Explain the commercial purpose and identify questions that need answers before a proposal can be accepted.
Tender
Present the same requirement to the selected lenders. Record where a lender proposes a different structure rather than treating every response as directly comparable.
Negotiate
Compare written terms and seek clarification on differences. Keep security, guarantees, fees, repayment obligations and settlement conditions in the discussion.
Settle
Check the final documents against the accepted proposal. Confirm responsibility for outstanding conditions and coordinate the equipment transaction before committing to settlement arrangements.
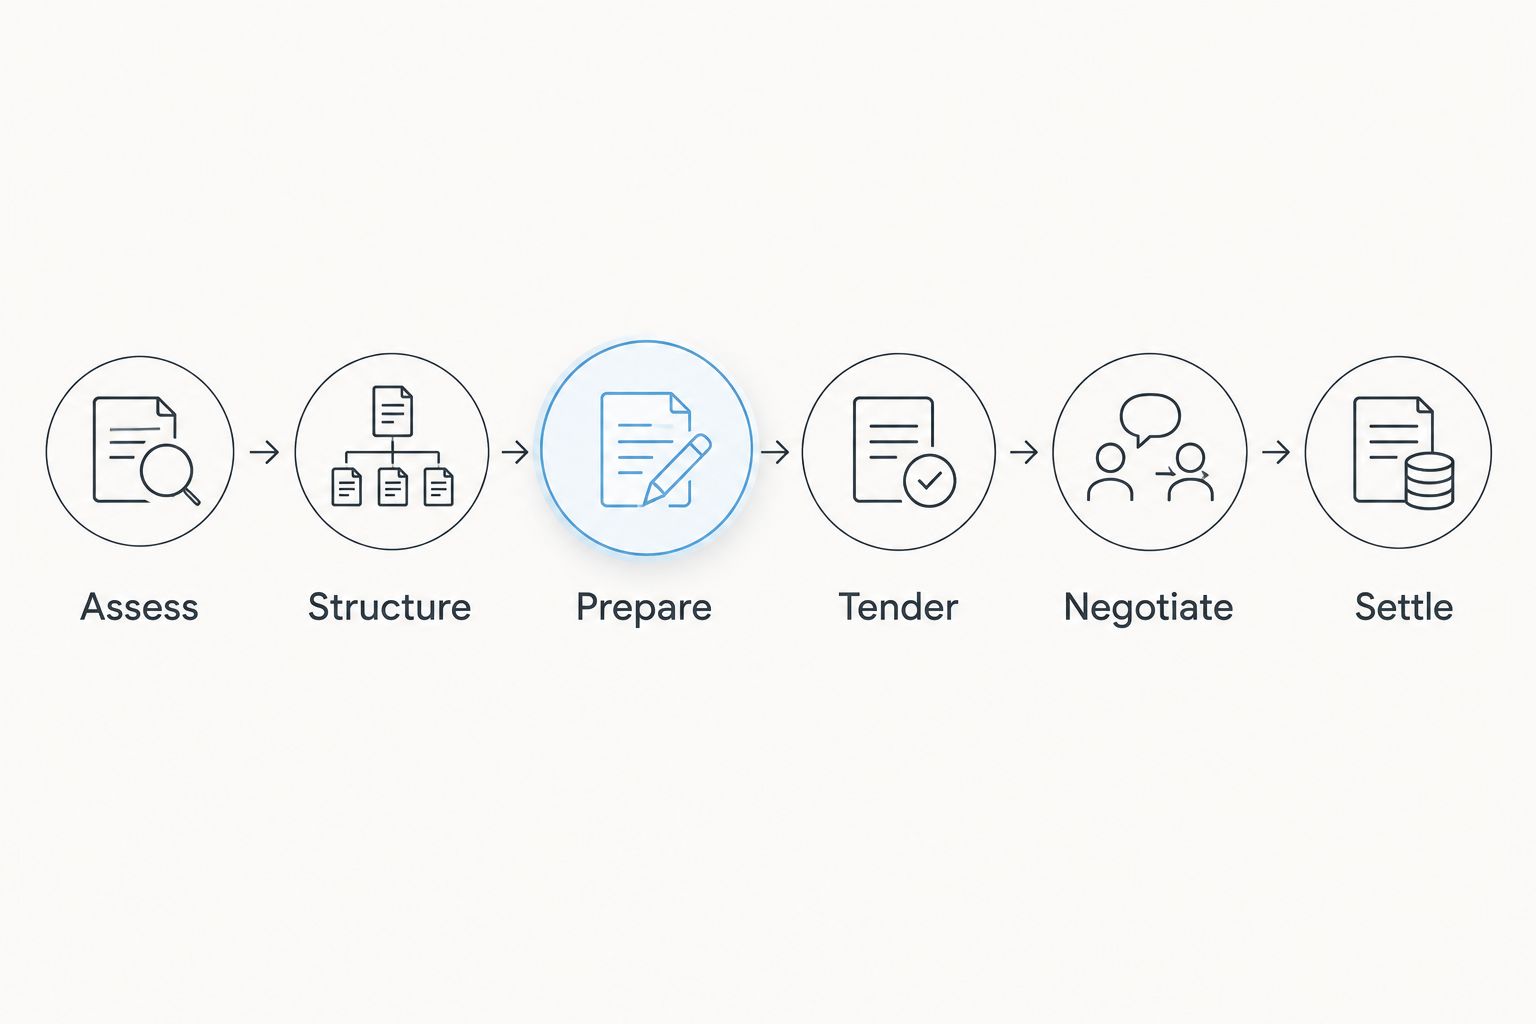
This process does not promise approval or a better offer. Its value is a clear record of the requirement, competing responses and reasons for the final decision.
Review your equipment finance structure
Discuss equipment borrowing alongside refinancing and your existing banking arrangements.
Check costs, security and remaining obligations
For a 2026 comparison, put the full written proposals side by side. Do not rank alternatives on the advertised interest rate alone.
| Check | Question to resolve |
|---|---|
| Repayments | What must the business pay, and when? |
| Residual debt | What remains payable at the end of the term? |
| Security | Which assets support the facility? |
| Guarantees | Who is being asked to guarantee the obligations? |
| Early repayment | What happens if you sell or replace the equipment early? |
| Conditions | What must happen before settlement? |
| Remuneration | Who pays the intermediary, and under which engagement? |
Distinguish lender-paid brokerage from debt advisory. Lender-paid brokerage involves remuneration from the lender; debt advisory uses a retainer and success-fee structure. Ask which arrangement applies to your engagement and obtain the terms in writing.
If proposals differ materially, ask for a revised comparison. Do not treat a shorter term, a different residual payment or broader security as a minor detail.
When staying with Westpac is the right call
Stay with Westpac when its documented proposal meets your requirements better than the alternatives after all material obligations are compared. Switching is not an achievement in itself.
Include the work and contractual consequences of changing arrangements in your decision. An alternative needs a business reason: suitable repayments, acceptable security, workable conditions or a better fit with your wider borrowing plan.
Keep the existing offer in the comparison. Rejecting it before competing proposals arrive removes a useful benchmark.
FAQ
What's the best Westpac alternative for equipment finance?
Glenclair suits owners seeking a broker-led comparison across a panel of 60+ lenders. NAB and Commonwealth Bank are direct bank alternatives; choose between written proposals based on your business requirements, not the provider's name.
Is NAB better than Westpac for equipment finance?
NAB is not automatically better than Westpac for equipment finance. Compare proposals for the same equipment, borrowing amount and repayment assumptions, including security and settlement conditions.
Should I use a commercial finance broker or apply directly?
Use a broker when you want help preparing the borrowing request and comparing suitable lenders. Apply directly when you want to manage the application and comparison yourself; the lender makes the credit decision in either route.
Can equipment finance be reviewed with existing business loans?
Yes, equipment finance can be considered alongside a review of existing business borrowing. Check how proposed security, guarantees and repayments interact with refinancing, working capital and property commitments.
Does lender-paid brokerage mean debt advisory has no separate fees?
No. Lender-paid brokerage and debt advisory are different engagements. Debt advisory uses a retainer and success-fee structure, so confirm the scope and remuneration that apply before proceeding.
Do I need to borrow more than A$2 million to enquire?
A$2 million is not a universal eligibility threshold in this guide. The focus is established business owners with substantial commercial borrowing needs, and suitability must be assessed case by case.
What should I request before switching equipment finance lenders?
Request written proposals that identify repayments, residual debt, security, guarantees, fees and settlement conditions. Check the consequences of changing existing arrangements before accepting an alternative.
One last thing
Ask every prospective lender to identify where its proposal differs from your original brief. That question exposes a comparison problem quickly: an attractive repayment can reflect a different borrowing structure rather than a better deal.
Choose the facility you can explain clearly—not the headline you like most.
Related guides
- Equipment finance options for construction businesses
- Equipment finance options for manufacturing businesses
- Truck finance options for Australian transport fleets
By the Glenclair Financial team.