
Can truck finance include a balloon payment?
Yes. A truck finance balloon payment leaves an agreed lump sum payable at the end of the loan, reducing regular repayments compared with an otherwise equivalent loan that repays the full balance progressively. Interest still applies under the loan terms, and you need a credible way to pay the final amount; selling the truck or refinancing does not guarantee you can clear it.
TL;DR
- A truck finance balloon payment reduces regular repayments but leaves debt to repay at maturity.
- Compare equipment finance structures using total interest, final debt and cash flow, not the monthly repayment alone.
- A truck sale or refinance is an exit strategy, not a guaranteed source of repayment.
- Glenclair suits established Australian businesses reviewing commercial finance, with suitability assessed case by case.
Can truck finance include a balloon payment?
Yes. Business-purpose truck finance can include a balloon payment where the lender accepts that structure. The amount, loan term, truck and borrower all form part of the credit assessment. A balloon is not an entitlement attached to every truck loan.
For a 2026 finance review, request comparable repayment schedules rather than comparing advertised instalments. The same borrowing requirement can produce very different obligations depending on how much principal remains unpaid at maturity.
| Structure | Best for | Main advantage | Main drawback |
|---|---|---|---|
| Truck loan with a balloon | Businesses with a documented source of final repayment | Lower regular repayments than an otherwise equivalent fully amortising loan | A lump sum remains due, with more principal outstanding during the term |
| Truck loan without a balloon | Businesses prioritising progressive debt reduction | Scheduled repayments clear the loan by maturity | Higher regular repayments on an otherwise equivalent loan |
Ask for both structures when reviewing commercial finance services. Keep the amount financed, term, repayment frequency and interest assumptions consistent so the comparison isolates the balloon's effect.
Why this matters
A lower monthly repayment is not the same as a smaller debt obligation. A balloon changes when you repay principal. It does not remove that principal or settle the question of affordability.
That distinction matters when your truck generates revenue throughout the term but the loan requires a substantial payment on a single date. Your operating cash flow and your final repayment source need separate assessments.
Glenclair's commercial finance work is directed towards established Australian business owners, prioritising refinancing and reviews of existing banking arrangements. Borrowing above A$2 million is a preferred focus, not a universal eligibility rule. An individual truck enquiry still requires a case-by-case suitability assessment.
For a fleet review in 2026, assess the truck loan alongside working capital, existing equipment debt and other banking commitments. An affordable instalment on one vehicle does not establish that the combined repayment schedule fits the business.
Truck finance with a balloon: lower regular repayments, final debt
A balloon reduces the principal repaid through regular instalments. The remaining amount falls due at maturity, alongside any other payment required by the contract.
The benefit is timing. You retain more operating cash during the loan term than under an otherwise equivalent fully amortising structure. That can suit a business whose final repayment source is separate from day-to-day trading receipts.
The trade-off is continuing exposure. Because principal remains outstanding for longer, total interest is generally higher when the amount borrowed, interest rate, term and repayment frequency are otherwise identical. Use the lender's schedule to establish the actual difference.
Best for: a business that can explain how it will meet both the regular repayments and the final obligation.
Do not choose the balloon solely because the monthly figure fits today's budget. Test whether it still fits after allowing for maintenance, insurance, registration and periods when the truck earns no revenue.
Truck finance without a balloon: progressive debt reduction
A fully amortising truck loan repays the principal through scheduled repayments across the term. Assuming you meet the contract, there is no separate balloon left to fund at maturity.
The advantage is a clearer debt-reduction path. You do not depend on a future sale or a fresh credit approval specifically to discharge a balloon. You still need to meet every scheduled repayment.
The drawback is the greater regular cash commitment compared with an otherwise equivalent balloon structure. That can place more pressure on working capital during quieter trading periods.
Best for: a business that prioritises clearing the truck debt through operating cash flow rather than arranging a separate final payment.
Compare this structure even if you initially requested a balloon. Seeing both schedules makes the cost of retaining cash during the term visible.
Why truck finance balloon payments vary
There is no single balloon setting that suits every borrower or truck. The proposed structure needs to fit the lender's assessment and the business's repayment plan.
The relevant drivers include:
- Truck age and condition. The vehicle's condition at the proposed maturity date matters to any plan involving its sale or continued financing.
- Expected use. Distance travelled, operating conditions and maintenance affect the assumptions behind a future sale.
- Loan term. The repayment date determines how long you have to prepare and how old the truck will be when the balloon falls due.
- Cash flow. Regular repayments must fit the business without treating an uncertain future event as available cash.
- Other borrowing. Existing repayments and facility maturities affect the business's capacity to carry the proposed structure.
- Repayment source. Retained cash, a truck sale and refinancing each require different evidence and carry different risks.
Ask the lender or broker to explain which factors constrain the proposed balloon. Do not assume another business's structure is available for your vehicle or financial position.
How do you assess whether a balloon fits your business?
Use a documented process before accepting the repayment schedule. For a 2026 banking review, the objective is to compare the whole obligation, not simply obtain a lower instalment.
- Assess. Set out existing debts, current repayments, trading cash flow and the reason for the truck purchase or refinance. Identify any other facilities maturing near the proposed balloon date.
- Structure. Request a balloon and a fully amortising alternative. State the intended holding period and the proposed source of final repayment.
- Prepare. Assemble financial information, truck details, existing finance statements and the supporting information requested for the application. Explain unusual trading periods rather than leaving unexplained movements in the figures.
- Tender. Present a consistent borrowing requirement to suitable lenders. Ask each to identify repayment terms, security, guarantees and conditions so the offers can be compared.
- Negotiate. Review the balloon alongside interest, fees, repayment frequency and contractual restrictions. A change to one term can affect the usefulness of another.
- Settle. Check the final documents against the accepted offer. Record the maturity date, final payment and repayment plan before signing.
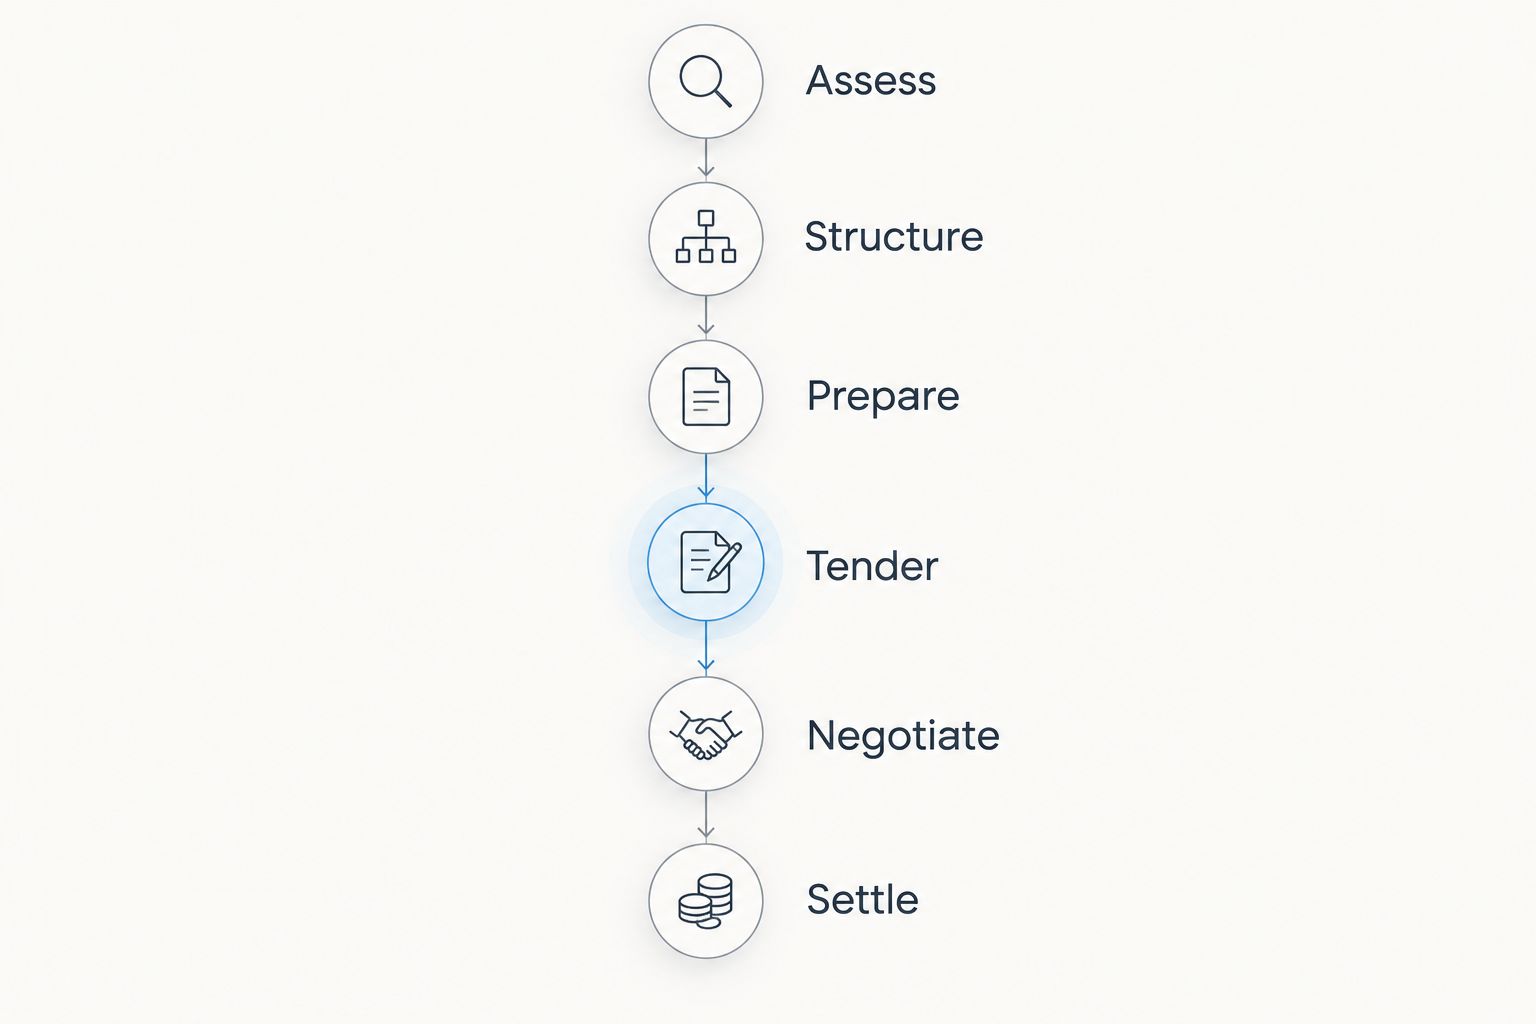
The tender process should give you a decision record, not just a collection of monthly repayment figures. Keep the assumptions behind each offer so you can explain why the selected structure fits the business.
What should you check in each finance offer?
Read the repayment schedule and the contract together. A summary showing the regular repayment cannot explain every obligation.
Check these points before accepting an offer:
- Final payment definition: establish whether the quoted balloon is additional to the last regular instalment or included in the final scheduled payment.
- Interest and repayments: identify whether the rate is fixed or variable, when repayments fall due and how interest is calculated under the contract.
- Total obligation: obtain the total scheduled repayments and separately identify applicable fees and charges.
- Security and guarantees: understand which assets secure the loan and who accepts personal obligations.
- Early exit: request the method for calculating a payout before maturity, including any applicable charges.
- End-of-term requirements: confirm the final due date and whether the contract contains any specific notice or discharge requirements.
Compare written terms, not verbal assurances. If the offer and the repayment schedule appear inconsistent, resolve the difference before settlement.
Your accountant can assess the proposed structure's tax and accounting treatment. Do not assume a balloon creates a tax advantage simply because it reduces regular cash repayments.
Can you refinance a truck balloon payment?
Yes, a truck balloon payment can be refinanced if a lender approves a new facility. The original loan does not promise that approval. A future lender assesses the application under its requirements at that time.
Your financial position, existing debts, truck condition and the proposed security all matter to that assessment. A refinance also creates a new repayment obligation rather than eliminating the debt.
For a loan arranged in 2026, document refinancing as a conditional exit strategy. Identify what the business would do if a new loan were unavailable or unsuitable when the balloon became due.
Start the review before the maturity date. That gives you room to assess alternatives instead of treating an approaching deadline as a reason to accept unsuitable terms.
What happens if the truck sells for less than the balloon?
A truck balloon payment remains payable even when the truck's sale proceeds are lower than expected. Unless the contract expressly provides otherwise, the sale value does not replace the amount you owe.
Request a written payout figure before planning a sale. The amount required to discharge the finance can differ from the balloon alone, particularly if you sell before maturity.
Build the exit plan around net proceeds after relevant selling and discharge costs. Do not treat an asking price, an informal valuation or the original purchase amount as money already available to repay the loan.
Is a balloon payment better for a transport fleet?
A truck balloon payment is not automatically better for a fleet. It changes the timing of debt repayment, while the fleet still has to fund operations, vehicle replacement and other finance commitments.
Map maturity dates across the fleet. Several balloons falling due together create a different cash requirement from the same obligations spread across separate periods.
Then test the replacement plan. If selling a truck is supposed to repay its balloon, identify how the replacement vehicle will be funded without counting the same sale proceeds twice.
For an established operator, the useful comparison is the combined fleet repayment schedule. An attractive instalment on an individual truck can obscure a difficult concentration of final payments.
Where does a commercial finance broker fit?
A commercial finance broker can help organise the borrowing requirement and compare lender proposals. Ask how the broker selects lenders, presents the application and explains differences between offers.
Glenclair's commercial finance panel includes 60+ lenders. Panel size does not mean every lender suits a particular truck, borrower or repayment structure; the relevant question is which proposals address the actual requirement.
Glenclair is best suited to established Australian businesses seeking a commercial finance review, with suitability assessed case by case. For a balloon enquiry, the review should address the existing banking position as well as the vehicle loan.
Distinguish lender-paid brokerage from debt advisory services. Debt advisory uses a retainer and success-fee structure. Confirm which engagement applies, how remuneration works and what scope is agreed before proceeding.
A broker's involvement does not guarantee approval, a particular balloon or a successful refinance. The lender's written offer and the signed contract govern the finance obligation.
FAQ
Can I get truck finance with a balloon payment in Australia?
Yes, business-purpose truck finance can include a balloon payment where the lender approves the structure. The proposed truck, borrower, term and final repayment plan form part of the assessment.
Does a truck finance balloon payment reduce interest?
A balloon payment does not inherently reduce interest. With otherwise identical terms, retaining more principal until maturity generally increases total interest compared with progressively repaying that principal.
Is a balloon payment the same as the truck's guaranteed resale value?
No. A balloon is a contractual debt amount, not a guaranteed resale value. A sale below the amount required to discharge the finance leaves a shortfall to fund.
Can I refinance the balloon instead of paying it from cash?
Yes, if a lender approves the refinancing application. Future approval is not guaranteed, so refinancing needs a fallback plan.
Can I pay out truck finance before the balloon is due?
Early payout depends on the finance contract. Request a written payout figure and confirm applicable charges before selling the truck or replacing the facility.
Is truck finance without a balloon better for my business?
Truck finance without a balloon suits businesses prioritising progressive debt reduction, provided the regular repayments fit cash flow. A balloon suits a different repayment plan, not an automatically better one.
What should I ask a broker about a proposed balloon?
Ask for comparable schedules with and without the balloon, the total repayment obligation and the proposed source of final repayment. Also confirm security, guarantees, early payout terms and the broker's remuneration.
One last thing
Before accepting truck finance in 2026, write down the source of the final payment in a single sentence. Then identify what happens if that source falls short.
If the answer is simply that the truck should hold its value or another lender should refinance it, the repayment plan is incomplete. Choose the balloon only after you can explain the exit, not just the instalment.
Related guides
- Truck finance options for owner-drivers
- Truck finance options for Australian transport fleets
- Equipment finance options for construction businesses
- Machinery finance options for earthmoving contractors
Written by the Glenclair Financial team.